When a Kid's Injury on the Field Becomes an Employer's $116,000 Claim

Teens are statistically one of the lowest-risk populations on a health plan. But low risk doesn't mean low cost. A serious youth sports injury can cost more than $100,000.
Nationally, 70% of emergency deparment visits for sports and recreation related traumatic brain injuries and concussions occur in children 17 years and younger. Specifically, boys’ football and girls’ soccer are consistently identified as the two sports most associated with serious injuries and concussions (CDC).
Our claims data show that when serious injuries happen, the costs land squarely on employers. Below, we dig into the data and share a few concrete steps that can protect young athletes, guide families through getting appropriate care, and keep costs from catching employer health plans by surprise.
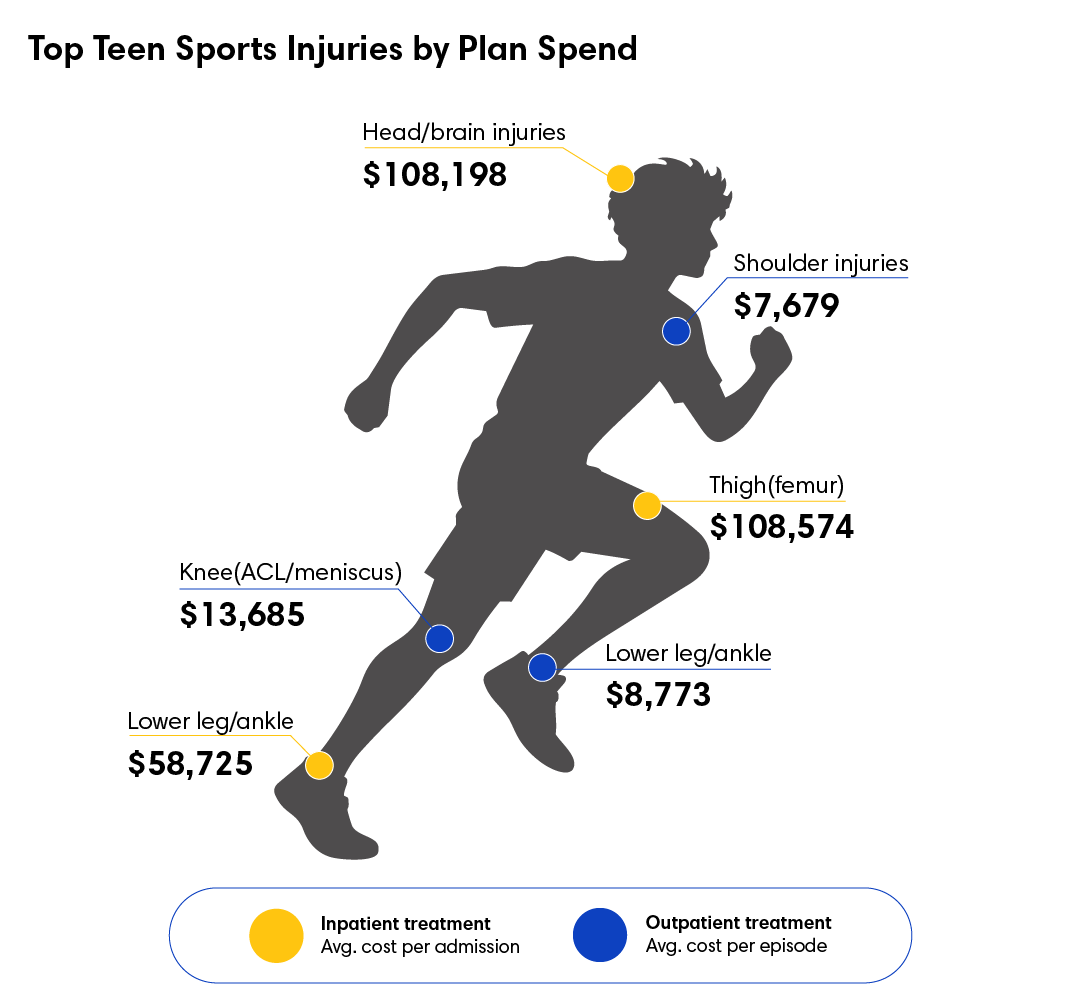
Artemis by Nomi Health looked at its self-funded book of business claims for roughly one million enrolled teens, ages 14-18, across 2024 and 2025, to quantify these not-so-obvious costs. In 2025, the average cost of an inpatient admission for a teen sports injury was just over $75,000. More severe cases, like intracranial injuries, ran $108,000 to $116,000 across the two years. Even average outpatient claims costs climbed 14% from 2024 to 2025.
Where the Costs Concentrate
The costs are concentrated in a handful of injuries. The infographic highlights the top three inpatient and outpatient injury categories by total medical and pharmacy claims spend, along with the average cost per admission or episode. Serious inpatient injuries can average more than $100,000, while even outpatient injuries can cost thousands per episode, showing how quickly youth sports injuries can become meaningful health plan spend.
A Seasonal Trend
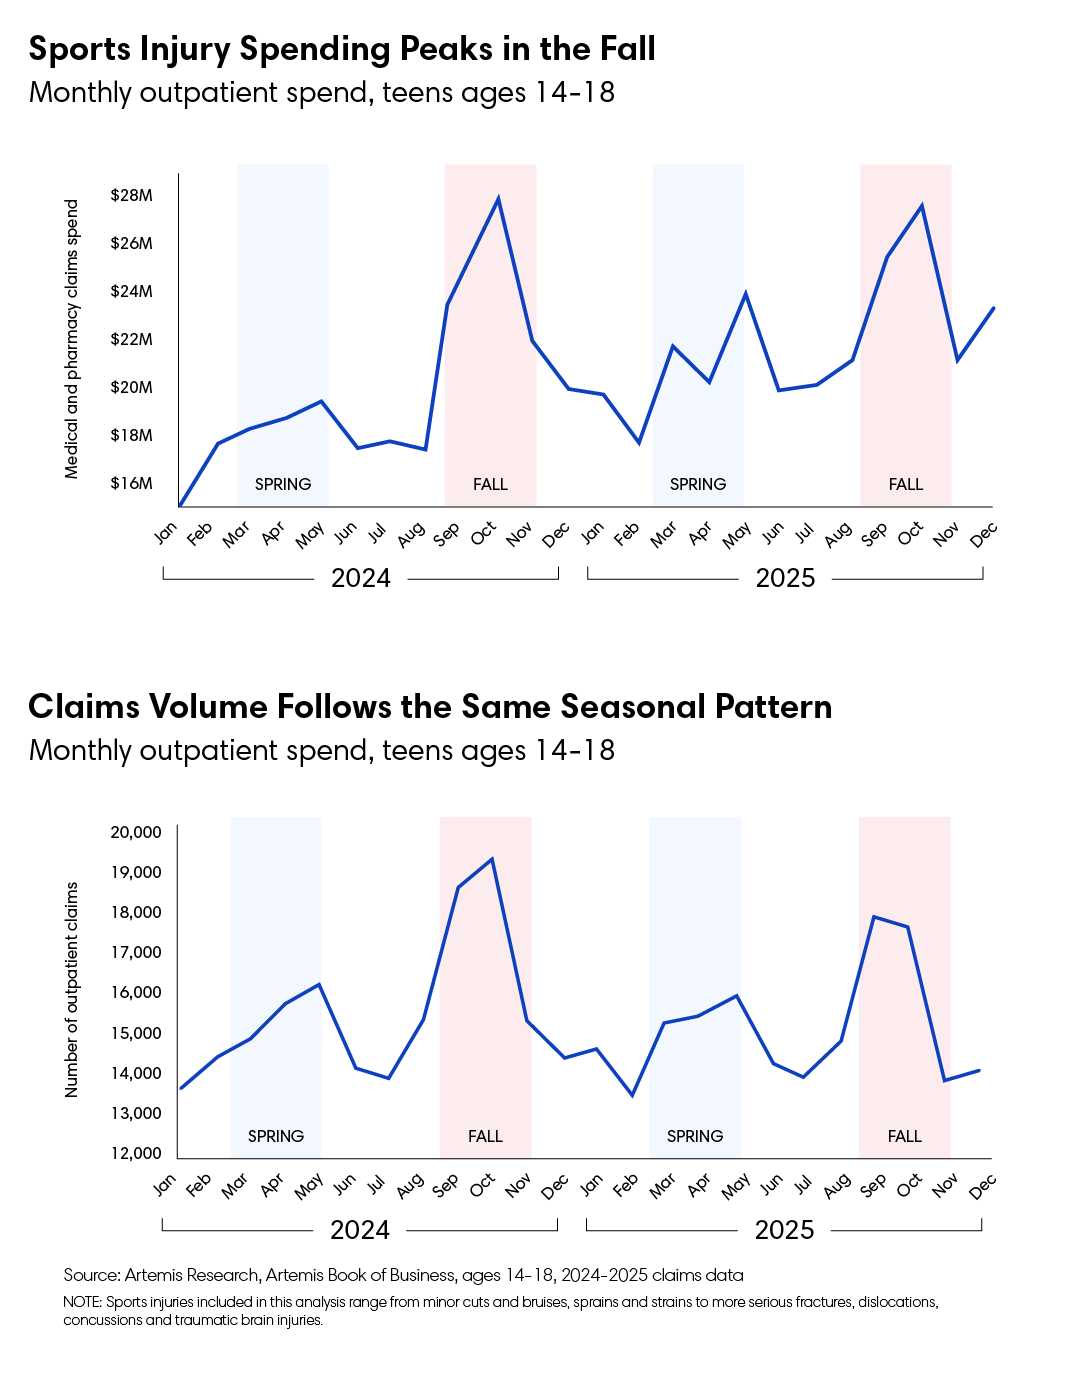
The claims data show a recurring seasonal pattern, with the most pronounced increases in the fall and smaller increases around the spring sports season. That pattern appears in both claims volume and total spend, suggesting the increase is broad-based rather than driven by a handful of unusually expensive claims.
What Employers Can Do
1. Prepare Before Peak Sports Seasons. An ounce of prevention goes a long way, so knowing the seasonal trends gives employers a rare advantage. Our claims data showed spikes in the fall and spring seasons. Preseason communications can remind parents about sport-specific protective equipment, conditioning, hydration, rest, and the signs of injuries that should not be ignored. Employers can also use this moment to highlight relevant benefits, including primary care, virtual care, nurse lines, musculoskeletal programs, and behavioral health support. This type of outreach can help families reduce injury risk, recognize warning signs earlier, and know where to turn when an injury occurs.
2. Clarify Coordination of Coverage. Treatment for injuries sustained during practices, games and competitions may be covered by school insurance, league liability coverage, or other family policies. Make sure employees understand how their child's team or league provides supplemental accident or sports injury coverage and how it coordinates with your health plan. Consider surfacing that information proactively rather than after a claim is filed.
3. Track the Trend in Your Own Claims Data. Sports injuries among teenagers may not be top of mind during a typical claims review, but the pattern can become visible well before the costs become a surprise. Employers should examine claims during the fall and spring peaks, identify the injuries driving inpatient and outpatient spending, and track where care is being delivered. Tools like Artemis make it possible to isolate this population, compare seasonal patterns, and identify the claims and care settings contributing most to the trend. That visibility helps employers decide where better communication, navigation, or plan management could have the greatest impact.
The Bottom Line
None of this means keeping kids off the field. It means recognizing that one of a plan's lowest-risk populations can still produce six-figure claims, and that the pattern behind it isn't random. Going into the season with that picture, and a plan for managing it, is what turns a surprise claim into a manageable one.